Professor Kissinger’s transformative coaching and practical tools on generational wealth mastery emphasizes deep insight mindset shifts, strategic planning for creating, preserving generational wealth while transitioning from a consumer mindset to an owner mindset to achieve abundance. Concrete coaching, strategies and tools that have transformed thousands of people at every financial life and business stage.
Transformative Experience – Mindset Shifting – Life-Changing – Actionable Wealth-Building Strategies – Practical Tools – Supportive Environment Preserving Wealth Across Generations
Discover the Secrets to Lasting Wealth: Strategies for Generational Prosperity
Professor Michael Kissinger and The Reitenbach Kissinger Institute emphasizes that wealthy families utilize mastery principles to create, build, and preserve generational wealth through strategic financial education and mindset shifts.
By adopting the psychology and tools of top investors, families can ensure their wealth is not only accumulated but also sustained across generations.
Financial freedom through Professor Kissinger’s MKS Master Key System Coaching involves mastering the psychology and strategies of elite investors to secure your future.
Rather than focusing on simple numbers, the approach centers on transforming your relationship with money, creating sustainable wealth-building habits, and shifting from a mindset of scarcity to one of abundance.
Professor Kissinger Advises Families to Structure a Family Office
| Core Pillar | Strategic Focus | Implementation |
|---|---|---|
| MKS Master Key System Wealth Mindset Coaching Shifts | Moving away from scarcity | Replacing limiting beliefs about affordability with actionable growth goals |
| MKS Master Key System Core Principles Coaching | Building lasting frameworks | Protecting your principal while seeking asymmetric returns and tax efficiency |
| MKS Master Key System Compound Growth Coaching Power | Leveraging consistent habits | Automating contributions to investments starting early to build wealth over time |
| MKS Master Key System Giving and Contribution Coaching | Attracting more abundance | Incorporating generosity into financial planning to open energetic channels for success |
Cultivating a Wealth Mindset
True generational success begins by examining the subconscious beliefs about money that often take root early in life. By shifting from a perspective of financial fear to one of personal empowerment, you can move toward a life designed on your own terms.
- Financial purpose clarity anchors your motivation, turning vague desires into measurable goals like passive income targets or specific savings milestones.
- Psychology of wealth helps you shed the internal barriers that cause you to plateau, allowing for more sustainable financial momentum.
- MKS Master Key System Generational Wealth Mastery Program Coaching provides the peer accountability and expert frameworks necessary to turn financial breakthroughs into automatic life practices.
Your journey toward lasting prosperity depends on these consistent habit shifts and the willingness to treat wealth management as a foundational skill.
Strategic Wealth Execution
Managing money effectively serves as the backbone of financial power, moving your strategy beyond mere account balances. Through proven investment frameworks, you can reduce risk and accelerate your path to security.
- Budgeting with intention allows you to align your daily spending habits with the values that matter most to your family’s future.
- Strategic debt elimination prioritizes high-interest obligations to ensure your capital is working for you rather than against you.
- Tax efficient investments rely on deep diversification and principal protection to help you grow smarter throughout different market cycles.
Taking control of your finances today is the surest way to build a legacy that provides security for your family in the years ahead.
Wealth Mastery Principles
Wealthy families implement specific strategies to maintain their financial legacy.
- MKS Master Key Generational Wealth System Financial Education — Wealthy families prioritize financial literacy, enabling informed investment decisions.
- MKS Master Key Generational Wealth Mindset Mastery System — They cultivate a wealth-oriented mindset, focusing on abundance rather than scarcity.
- MKS Master Key Generational Wealth System Strategic Planning — Long-term financial strategies are developed to ensure wealth preservation and growth.
- MKS Master Key Generational Wealth System Investment in Assets — Wealthy families often invest in appreciating assets, such as real estate and stocks, to build wealth.
- MKS Master Key Generational Wealth System Legacy Planning — They engage in estate planning to pass on wealth effectively to future generations.
Mindset Shifting — Wealth begins with a mindset that views money as a tool, not an end goal
Professor Kissinger’s coaching creates a new financial reality by empowering individuals with strategies for wealth creation, mindset shifts, and actionable insights tailored to their unique situations.
His approach combines psychological principles with practical financial advice, enabling clients to break through limiting beliefs and achieve financial freedom.
Financial success begins with shifting your internal psychology to overcome limiting beliefs, a foundation that Professor Kissinger argues accounts for 80% of wealth-building results while the remaining 20% covers mechanics.
By addressing how you approach money and replacing scarcity-based thoughts with an abundance mindset, his coaching aims to transform your daily financial reality.
Key Aspects
Professor Kissinger MKS Master Key Coaching System focuses on several transformative elements.
- Mindset Shift — He emphasizes the importance of changing one’s money mindset to overcome limiting beliefs and foster a wealth-oriented perspective.
- Wealth Strategies — He provides actionable strategies for wealth building, including investment tips and passive income generation.
- Personalized Coaching — Professor Kissinger tailors his coaching to individual needs, ensuring that clients receive relevant advice that aligns with their financial goals.
- Emotional Mastery — His coaching integrates emotional intelligence, helping clients manage fear and anxiety related to finances
Professor Kissinger’s Financial Coaching Program Work for Beginners
| Focus Area | Core Strategy | Intended Result |
|---|---|---|
| MKS Master Key System Psychological Foundational Coaching | Removing limiting beliefs about money | Transforming fear into productive action |
| MKS Master Key System Systematic Process Coaching | Creating disciplined rules for trading | Removing emotional bias from decisions |
| MKS Master Key System Wealth Habits Coaching | Automating investment of income | Building assets through consistent growth |
Mastering the Money Game
The underlying psychology of your financial life determines whether you master money or let it master you, according to Professor Kissinger. His coaching emphasizes that emotional triggers—such as fear, greed, or the desire for instant gratification—often cause investors to sabotage their own long-term success.
- Financial freedom serves as the primary goal, achieved by connecting specific actions to a deeper purpose and utilizing measurable SMART goals.
- Priming routines involving gratitude and posture adjustments allow you to change your emotional state instantly when reviewing financial statements or investment performance.
- MKS Master Key Generational Wealth System Systematic Processes replace gut-feeling decisions with checklists and criteria, which helps investors maintain discipline even during periods of high market volatility.
Mechanics of Wealth Building
Building wealth effectively relies on the power of compounding rather than needing an immense starting fortune. By automating savings and shifting your perspective from that of a consumer to an owner of assets, you can capitalize on the same wealth-generating systems used by major investors.
- Asset allocation acts as the cornerstone of financial security, ensuring that you manage risk rather than simply chasing the highest possible returns.
- Diversified portfolios spread risk across various sectors, geographies, and asset classes to smooth out returns and provide a more stable foundation.
- Pay yourself first principles ensure that a portion of your income is prioritized for investments before any other bills or discretionary expenses are addressed.
One final key to sustaining this growth is maintaining a long-term perspective, as financial independence is a marathon that rewards patience and consistent action over rapid, speculative gains.
Many individuals appreciate this approach to wealth creation and generational wealth building. Emphasizing not just financial gain but also personal growth and purpose.
Diverse Generational Investments — Explore various investment strategies tailored for different life stages, especially retirement.
To build and preserve multigenerational, “old money” wealth, you must shift from active income generation to systemic capital preservation and structured compounding.
Establish the Governance Framework
- Family Office Structure: Establish a single-family or multi-family office to centralize investment, legal, and tax management.
- Private Trust Instruments: Utilize irrevocable trusts, generation-skipping transfer (GST) trusts, and dynasty trusts to shield assets from litigation, divorce, and estate taxes.
- The Family Constitution: Draft formal governance documentation defining the family’s financial philosophy, voting rights, and distribution rules.
- Perpetual Capital Rules: Enforce a strict mandate where only a fraction of investment returns (typically 3% to 4%) can be spent, keeping the principal untouched.
Optimize the Asset Allocation System
- Core-Satellite Investment Framework: Place 75% to 80% of capital into foundational, low-risk preservation assets and 20% into high-growth “satellites.”
- Direct Private Equity: Bypass traditional public markets to acquire controlling or significant minority stakes in private, cash-flowing businesses.
- Institutional Real Estate: Focus on premium commercial real estate, agricultural land, and high-density residential properties for inflation-hedged yields.
- Farmland and Timberland: Invest heavily in non-correlated, tangible commodities that yield steady, long-term operational cash flows.
- Alternative Credit Systems: Engage in private lending, mezzanine financing, and structured debt to act as the bank, securing high-yield senior positions.
Implement Capital Preservation Mechanics
- The Sovereign Diversification Strategy: Distribute institutional custody and physical assets across multiple legal jurisdictions to mitigate geographic risk.
- Value-Investing Core System: Anchor public equity allocations in deeply undervalued, wide-moat blue-chip corporations with a history of increasing dividends.
- Tax-Efficient Asset Location: Structure investments through tax-advantaged vehicles like Private Placement Life Insurance (PPLI) to allow tax-free compounding.
- Physical Asset Vaulting: Maintain a dedicated percentage of net worth in physically secured, non-digitized allocations like physical precious metals.
Manage Cash and Leverage Systematically
- Strategic Arbitrage Cash Management: Keep massive liquidity reserves in ultra-short-duration Treasury bills to instantly exploit market liquidations and distress.
- Non-Recourse Asset-Based Lending: Utilize security-backed lines of credit (SBLOCs) to fund lifestyle or new acquisitions without triggering capital gains taxes.
- The Infinite Banking Concept: Deploy high-cash-value whole life insurance structures to self-finance major family investments while compounding capital simultaneously.
Build Generational and Legal Safeguards
- Multigenerational Financial Apprenticeship: Require heirs to complete formal financial training and external professional work before gaining trust access.
- Incentive-Based Trust Distributions: Match trust distributions to constructive milestones like completing higher education, starting a business, or philanthropic leadership.
- Aggressive Entity Isolation: Separate every major business asset, property, and investment portfolio into distinct LLCs and holding companies.
- Philanthropic Capital Systems: Establish private family foundations or Donor-Advised Funds (DAFs) to eliminate tax liabilities while training heirs in capital management.
Implement Wealth Preservation Systems: Elite Families Teach Their Children
“Old money” families build lasting generational wealth by prioritizing financial literacy over consumption. Instead of simply handing children lump sums, they install systems that teach kids to think like owners, leverage compound interest, and view money as an actual tool t acquire productive assets.
Wealthy families use specific educational and structural systems to pass down financial wisdom. These methods focus on capital preservation, stewardship, and entrepreneurial skills.
These core systems and frameworks demonstrate exactly how wealthy families train their children to earn and invest millions:
Lay The Foundation: Mindset & Financial Literacy
- View Money as Unlimited: They teach that wealth is not a finite pie to be fought over, but an expanding resource that rewards problem-solving and creation.
- Prioritize Long-Term Horizons: Where most think in weeks or quarters, old money families plan in decades or centuries, focusing on legacy rather than instant gratification.
- Become Fluent in the Language of Wealth: Children are taught to read balance sheets, understand compound interest, and casually discuss market trends.
- Treat “Work” as Ownership: Heirs are taught early on that trading time for a salary creates a glass ceiling. The focus is always on owning the asset or business that hires the workers.
- Differentiate Assets vs. Liabilities: They engrave the rule that money must flow into their pockets (assets) rather than just flowing out (liabilities).
Create Strategic Earning: Business & Leverage
- Start Small, Scale Fast: Children are encouraged to run micro-businesses (e.g., e-commerce, services, or crafts) early on to understand the basics of profit, loss, and customer acquisition.
- Solve High-Value Problems: They are coached that earning millions comes from addressing massive, scalable problems rather than small, local ones.
- Master the Concept of Leverage: They teach kids to use OPM (Other People’s Money) and OPT (Other People’s Time) to multiply their own earning capacity.
- Build Multiple Income Streams: Millionaires rarely rely on a single paycheck. Heirs are taught to build 5 to 7 diverse revenue streams like investments, royalties, and business profits.
- Embrace Calculated Risk: Old money families view failure as data. They teach children to identify asymmetrical risks where the potential upside is in the millions and the downside is controlled.
Accumulate Wealth: Growth & Protection
- Start Compounding Early: They put money to work in tax-advantaged vehicles (like 529s or Roth IRAs) the moment a child is born, giving compounding interest the longest possible runway.
- Understand the Tax Code: Instead of seeing taxes as a burden, they teach kids to use tax-efficient investment structures to accelerate growth and keep what they earn.
- Invest in Real Estate: It is the bedrock of generational wealth. Heirs are taught how to leverage real estate for cash flow and long-term appreciation.
- Avoid Lifestyle Creep: Even as income grows, they maintain a wide gap between their earnings and spending, reinvesting the surplus rather than inflating their expenses.
- Buy Time, Not Just Things: Children are taught to outsource low-value tasks so they can focus on high-value activities, strategic thinking, and networking
Build the Mindset
- The “Owner” Mentality: Teaching kids to invest in assets that produce cash flow, rather than purchasing depreciating liabilities or consumer goods.
- Deferred Gratification: Practicing patience. The ability to hold off on instant rewards builds self-control and long-term planning.
- Financial Literacy as Identity: Viewing financial management not as a chore, but as a core family duty and identity.
- Value of a Dollar: Requiring children to work for things they want, teaching them the effort required to earn capital.
- Saying “No”: Explaining why certain expensive purchases aren’t worth the money, teaching children to weigh the actual utility of an item.
Early Education & Mindset
- The Four-Jar System: Dividing allowances into distinct buckets for spending, saving, investing, and charity.
- Family Bank Simulation: Acting as a lender to teach children how interest works through real loans.
- Boardroom Exposure: Inviting teenage children to sit in on real business meetings as observers.
- The “Producer” Filter: Training kids to view products as business owners rather than everyday consumers.
- Delayed Gratification Benchmarks: Matching a child’s savings to reward long-term financial patience and discipline.
Systematic Investing and Systems
- Custodial Stock Portfolios: Allowing children to pick stocks from companies they use in daily life.
- Compounding Visualizers: Using charts to show how small, early investments grow over fifty years.
- The 10% Innovation Rule: Letting heirs manage a tiny fraction of wealth in high-risk startups.
- Generational Real Estate Walks: Touring physical properties together to explain equity, debt, and cash flow.
- Mock Portfolio Competitions: Gamifying market tracking between siblings using fake money with real rewards.
Family Governance
- Junior Family Councils: Organizing formal meetings where the next generation practices making group decisions.
- Family Constitutions: Writing a shared document that outlines the core financial values of the family.
- The Three-Generation Rule: Explicitly studying how past global families lost wealth to avoid repeating mistakes.
- Philanthropic Allocations: Giving children control over a charitable budget to teach impact and management.
- Legacy Mentorship Matches: Pairing young adults with trusted family advisors, lawyers, or top accountants.
Wealth Preservation
- Trust Fund Transparency: Revealing trust structures slowly based on age and emotional maturity milestones.
- Pre-Nuptial Education: Normalizing legal protections early so they are viewed as standard business practices.
- Asset Protection Basics: Teaching the legal separation between personal identity and corporate entities.
- Debt Discrimination: Training heirs to sharply differentiate between productive leverage and destructive consumer debt.
- The Stealth Wealth Protocol: Emphasizing low-profile living to protect the family from financial predators.
Advance Financial Education Systems
- The Family Bank: Children pitch business ideas to a family board for loans.
- Matching Investment Funds: Parents match 1:1 every dollar a child saves and invests.
- Shadow Board Seats: Young adults sit in on board meetings as non-voting observers.
- Phased Trust Distributions: Trust funds unlock only at specific milestones like ages 25, 30, and 35.
- Mandated External Employment: Children must work outside the family business for several years first.
- Family Philanthropy Committees: Kids manage a small charitable budget to learn capital allocation.
Optimize Mindset & Capital Systems
- Human Capital Priority: The family funds unlimited education but restricts lifestyle handouts.
- Social Capital Training: Youth attend curated networking events to build high-net-worth relationships.
- Fail-Safe Funding: Families provide a safety net for business failures, treating losses as tuition.
- The 10% Reinvestment Rule: Families mandate that 10% of all personal earnings go back into investments.
- Annual Wealth Summits: Multi-generational retreats are held to review total family asset performance.
- Legacy Storytelling: Regular history lessons detail how past ancestors built and lost family fortunes.
Master Social Capital & Networks
- Boardroom shadowing: Sitting in on corporate meetings early.
- Mastering soft power: Learning high-stakes negotiation via family dinners.
- Leveraging introductions: Using family connections for early-stage capital.
- Philanthropic leadership: Managing charity galas to build elite networks.
Allocate Capital & Investments
- Trust fund matching: Matching the child’s earned income with investment capital.
- Simulated portfolio management: Mandating childhood investing using real family office data.
- Angling for equity: Prioritizing stock options over base salaries.
- Generational debt mechanics: Using low-interest family bank loans to buy assets.
Consider Entrepreneurship & Business Systems
- Intraprenuership mandates: Launching a new subsidiary inside the family business.
- The “Clean Slate” rule: Funding a brand-new business outside the family domain.
- System acquisition: Buying existing cash-flowing businesses instead of starting small.
- Licensing and IP: Creating scalable intellectual property like software or brands.
Real Estate & Hard Assets
- Live-in development: Buying distressed property, renovating it, and flipping it.
- Commercial syndication: Co-investing in multi-family units using family equity.
- Land banking: Teaching the long-term appreciation value of zoning changes.
- Asset-backed lending: Using family hard assets as collateral for new ventures.
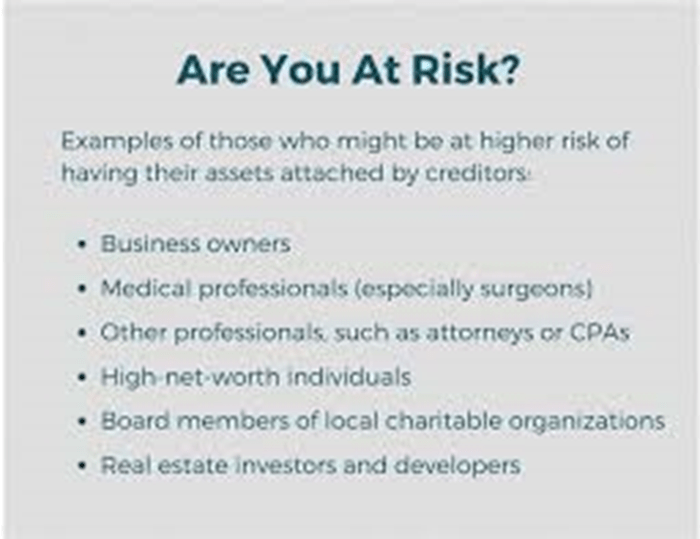
Use Old Money Asset Protection
Old money” wealth preservation relies on systemic asset protection rather than a single silver bullet, combining legal entity structuring, tax-efficient trusts, and diversified capital allocation to shield assets from lawsuits and generational wealth depletion.
The core asset protection and wealth-building mechanisms used by high-net-worth families include:
1. Legal Entities & Risk Separation
- Family Limited Partnerships (FLPs): Allows you to retain control of assets as the general partner while gifting limited partnership units to family members, shielding assets from the creditors of limited partners.
- Family Holding Companies: Parent entities that own various subsidiary LLCs, preventing a liability in one business venture (e.g., real estate) from touching the rest of your wealth.
- Limited Liability Companies (LLCs): Utilized to isolate operational liabilities; single-member or multi-member structures use charging orders to prevent creditors from seizing company assets.
- Series LLCs: Allows for the creation of separate, distinct series within a single LLC, each with its own assets, members, and liabilities.
2. Trust Structures
- Irrevocable Trusts: Assets placed here are legally removed from your estate, shielding them from future lawsuits, creditors, and estate taxes.
- Asset Protection Trusts (APTs): Specialized trusts (often domiciled in jurisdictions with favorable laws like Nevada or the Cook Islands) designed to protect assets from claims while allowing you to remain a beneficiary.
- Dynasty Trusts: Designed to last for multiple generations, avoiding estate taxes across generational transfers.
- Special Needs & Spendthrift Trusts: Provides asset protection and controlled distributions to heirs, protecting the principal from the heir’s future creditors or reckless spending.
- Charitable Remainder Trusts (CRTs): Irrevocable trusts that allow you to put highly appreciated assets into a trust, receive income for life, and distribute the remainder to charity, bypassing immediate capital gains taxes.
- Grantor-Retained Annuity Trusts (GRATs): An estate planning tool used to transfer wealth to family members with minimal to no gift tax, moving future appreciation out of your taxable estate.
3. Capital Allocation & Investment Vehicles
- Private Placement Life Insurance (PPLI): High cash-value life insurance policies used by ultra-high-net-worth individuals to grow investment portfolios tax-deferred and shield assets from lawsuits.
- Captive Insurance Companies: Creating your own licensed insurance company to underwrite the risks of your operating businesses, transforming risk costs into tax-deductible premiums.
- Family Offices (Single or Multi-Family): Dedicated private wealth management advisory firms that handle investments, asset protection, and tax planning.
- Offshore Accounts & Structures: Utilizing international banking jurisdictions with strong privacy laws and creditor-protection thresholds.
4. Generational Governance
- Family Charters: Formal, legally binding or socially enforced constitutions that dictate how the family’s wealth, business, and assets are managed, preventing family disputes.
- Private Foundations: Nonprofit legal entities that help manage philanthropic capital, ensuring continuous family control and legacy.
- Buy-Sell Agreements: Operating agreements that restrict who can buy into a family business, protecting shares from being sold to outside creditors or hostile parties in the event of a divorce or death.
- Uniform Transfers to Minors Act (UTMA) & 529 Plans: Used to transfer and protect wealth for younger generations while retaining tax-advantaged growth.
- Asset-Backed Lending (The “Buy, Borrow, Die” Strategy): Instead of liquidating assets and triggering capital gains taxes, wealthy individuals borrow against their asset portfolios to fund investments or living expenses, preserving principal.
Cultivate the Secrets to Lasting Wealth: 100% Financial Breakthroughs
Step 1 Personalized Call
In this 15-60 minute session, we will start to deep dive with you on what your biggest financial challenges, disputes or goals are and any current challenges you are having with achieving them.
Step 2 Match You
We’ll match you with a coaching strategist to help you uncover the root cause to what’s truly stopping you from getting what you financially want.
Step 3 Results Coaching Plan that Exceeds Expectations
You’ll get started with the Reitenbach Kissinger Institute Financial Coaching Team and close the gap to where you want to be quickly and efficiently.
Informed by four decades of extraordinary results, Michael Kissinger‘s Results Coaching is built to help you discover ways to grow your finances and profits exponentially. He provides the tools for you to create massive, lasting change in your life finances, and business.
It significantly reduces costs, prevent delays, and improves financial outcomes by identifying issues early and ensuring robust documentation and communication throughout the lifecycle.
It provides proactive strategies—such as comprehensive money management and thorough record-keeping—proves far more cost-effective than adversarial resolution processes. Research shows that effective money management can prevent project wealth generational failure and cost overruns achieve favorable outcomes.
“The path to financial success is to take massive, determined action.”
If not now, then when?
Consider the Alternative…FAILURE
Poverty to Lasting Long Term Wealth
Professor Kissinger’s MKS Master Key Generational Wealth coaching options and programs vary widely in format and cost, ranging from entry-level digital collections to intensive, multi-year certification tracks.
Whether you are looking for professional coaching or training or personal growth strategies, the investment depends on the depth of the commitment and the level of direct mentorship provided.
MKS Master Key System Generational Wealth Growth Coaching typically ranges from $6,995 for a MKS Master Key System Business Results plan to $4,500 to $18,000+ for multi-month or annual packages.
Understanding the pricing structure can help in decision-making.
- MKS Master Key System Generational Wealth Results Plan — Costs around $6,995 for a structured coaching program.
- MKS Master Key Generational Wealth System Multi-Month Packages — Range from $4,500 to $18,000+, depending on the duration and services included.
- One-on-One Coaching — Prices can vary significantly, often between $500 to $3,000 per hour.
- Annual Coaching Programs — Results Coaching can range from $15,000 to $75,000 per year.
Professor Kissinger’s Legacy
Professor Michael Kissinger is an owner and executive business coach, performance strategist, and former academic who operates the Reitenbach-Kissinger Success Institute and the MKS Master Key Coaching
Based out of San Francisco, California, he has spent over four decades working over 5,000+ business owners as a confidential business manager, analyst, and speaker focused on small business growth, leadership, and financial freedom.
Core Programs and Methodology
- The MKS Master Key Generational Wealth System: A structured, diagnostic framework built around six distinct core pillars: mindset, wealth, health, relationships, business, and leadership. The philosophy emphasizes that success is 80% psychology and 20% mechanics.
- MKS Master KEy Generational Wealth Strategic Makeover Sessions: The institute offers targeted diagnostic sessions designed to audit business growth levers and outline scalability tracks for companies generally yielding between $400,000 and $3 Million in annual revenue.
- Contracted Engagements: Programs are heavily tailored to custom small business, corporate or personal timelines rather than flat-rate fees. Standard six-month operational contracts typically range from $4,500 to over $8,200 depending on the scope of the dynamic tracking involved.
Academic and Professional Background
- Teaching Career: He served over 17 years as an adjunct professor instructing courses in business and law at multiple California institutions, including San Francisco State University, Golden Gate University, and Cañada College where he coached and trained over 10,000 university students and small business owners. Author of over 14,000 LinkedIn Articles that have created 18,650 followers and contacts.
- Martial Arts and Other Accomplishments: He holds a 4th Degree Kukkiwon Certified Taekwondo Black Belt and has active ties spanning 40 years as an instructor at the Reitenbach Institute of Taekwondo. He is a former US Army Honorably Discharged Special Forces Vietnam Member. He also served over 20 years as a minister at Unity Church and St Stevens Church.
You can view his complete professional breakdown directly on his LinkedIn Profile.

Let‘s Get Started on Lasting Wealth
Are you looking for specific generational wealth creation details to schedule a diagnostic session, or would you like a breakdown of a particular coaching to get rich? Contact us.
Professor Kissinger emphasizes the importance of continuous improvement as a key to personal, business, financial and professional growth. By constantly acquiring new knowledge and skills, individuals can adapt to changes, overcome challenges, and achieve their goals more effectively.
Continuous learning and improvement is a fundamental principle in Professor Kissinger’s coaching philosophy.
- Adaptability — Continuous improvement helps individuals adapt to changing circumstances and environments.
- Skill Development — Regularly updating and improving skills can lead to better performance in both personal and professional settings.
- Resilience — Learning and updating new strategies and perspectives fosters resilience, enabling individuals to navigate challenges more effectively.
- Goal Achievement — Lifelong learning and improvement is essential for achieving long-term goals, as it equips individuals with the tools needed for success
Contact to discuss how leverage, ownership, scalability, necessity, attention, and compounding can create completely different financial outcomes for you.
- Reitenbach Kissinger Institute
- Sydney Reitenbach
- Professor Michael Kissinger
- Text: 650-515-7545
- Email: mjkkissinger@yahoo.com
- Reach Your Peak Performance Results. Embrace Your Unlimited Potential. Valued Between from $2,350 to $5,500+
- This is a Free event, but you need to Contact us, Qualify and Register


